Recover municipal revenue with greater precision.
Distinguish genuine vulnerability from avoidable non-payment, then intervene before arrears become entrenched.
Discuss cities
Financial intelligence for a fairer tomorrow
SimONE helps cities, utilities and lenders identify financial vulnerability earlier and improve outcomes.
Illustrative graphic. Not client data. Scoring methodology is proprietary and is never shown to the customer.
The information gap
Traditional systems see a missed payment. They rarely see the event that caused it, or what could restore payment behaviour.
SimONE distinguishes temporary stress, structural vulnerability and avoidable non-payment, then adapts the journey.
Vulnerability intelligence becomes useful when it changes the message, timing, channel and escalation path.
How SimONE works
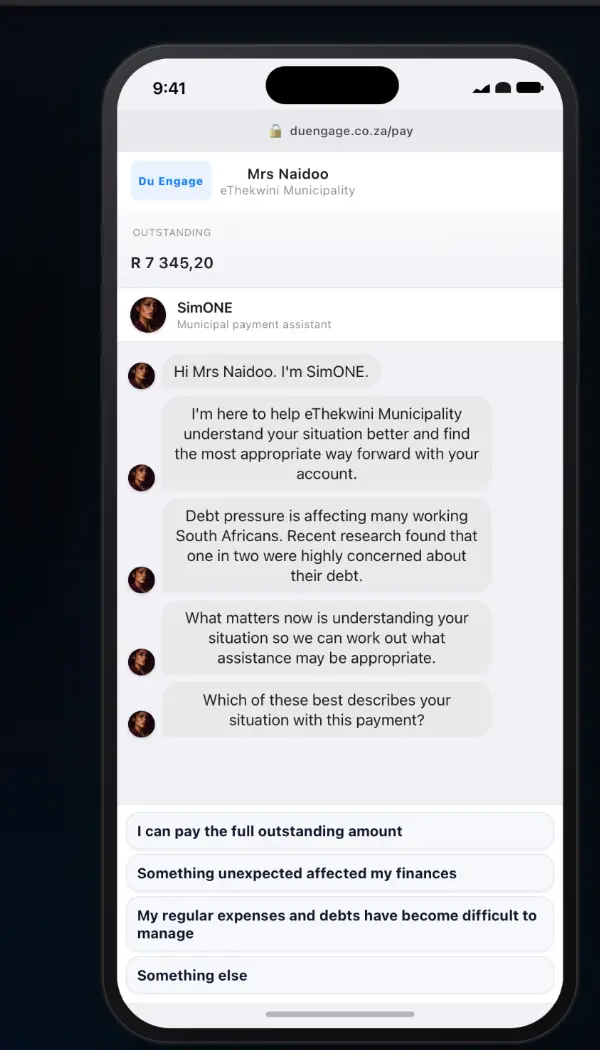
A guided conversational journey captures structured context, calculates vulnerability in real time and adapts the next step within institutional policy.
A low-friction WhatsApp journey meets the customer where they already are.
Structured questions reveal payment stress, household shocks and willingness to resolve.
FVRSI turns each response into a live financial vulnerability signal.
The journey, message and escalation path change as the customer profile changes.
Outcomes improve segmentation, journey design and future interventions.
Financial Vulnerability Risk Scoring Index
FVRSI combines observed behaviour and structured conversational data to reveal risk that a billing or loan ledger cannot see on its own.
Designed for institutional use. The internal vulnerability score informs segmentation and journey logic. It is not shown to the customer, and the scoring methodology is proprietary.
| 10 | Indigent |
|---|---|
| 9 | Incapacitated |
| 8 | Fired & Overindebted |
| 7 | Long-term Jobless |
| 6 | Acute Job Loss |
| 5 | Moderate Emergency |
| 4 | Overindebted |
| 3 | Marginal Stress |
| 2 | Transactional Failure |
| 1 | Willful Non-payment |
Adaptive engagement
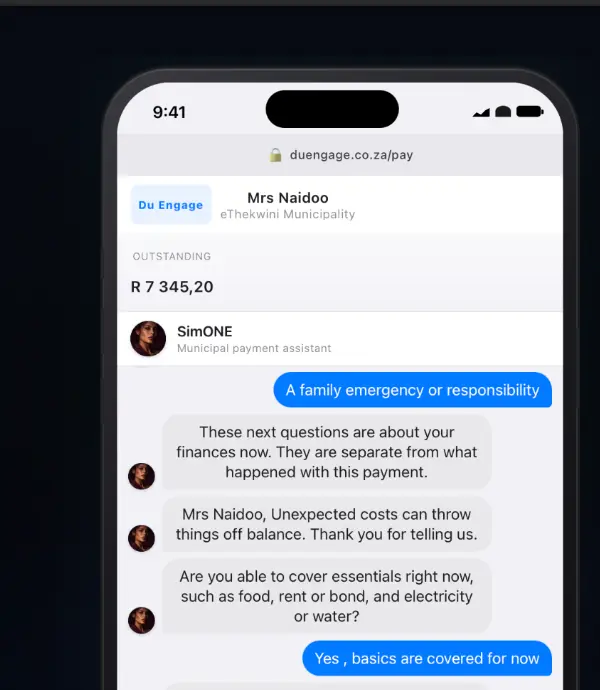
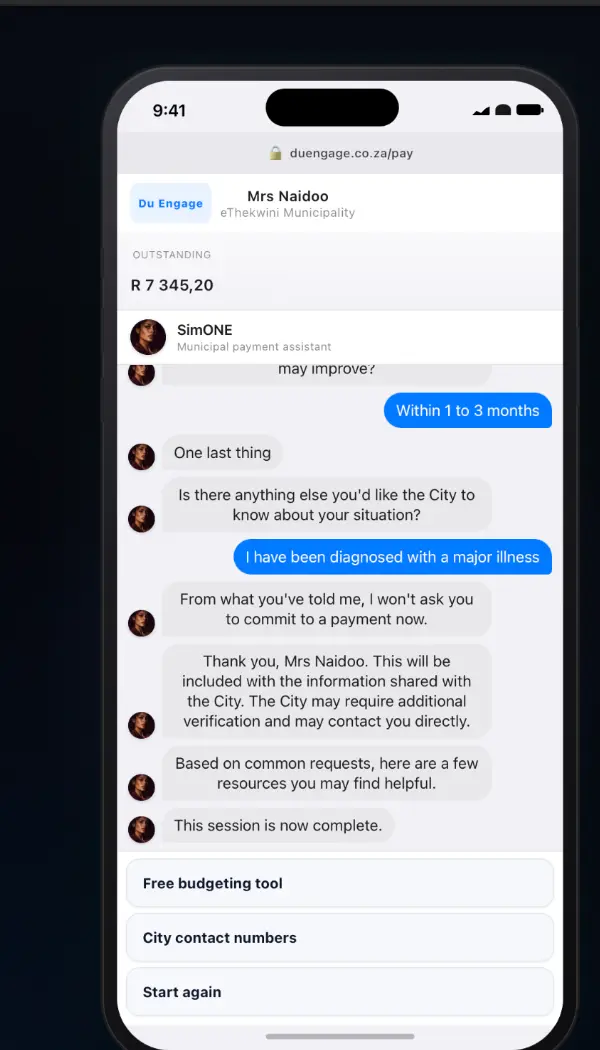
The customer is not pushed through a fixed script. SimONE adjusts the depth, language, timing and next action as new information arrives.
AI informs scoring, segmentation and journey adaptation. Consequential actions remain constrained by deterministic institutional rules.
One intelligence layer. Three revenue environments.
Distinguish genuine vulnerability from avoidable non-payment, then intervene before arrears become entrenched.
Discuss citiesAdd customer context to portfolio signals, improve digital engagement and protect long-term repayment behaviour.
Discuss lendersSeparate inability, disruption and avoidable non-payment to improve recovery while protecting essential services.
Discuss utilitiesBanking-grade AI today
SimONE separates probabilistic intelligence from consequential action. This contains hallucination risk, preserves auditability and lets institutions operate amid changing regulation.
Compliance by design
Data residency, access control, traceability and policy constraints are treated as product requirements from the first architecture decision.
Proof
Evidence from a 15,000-account champion-challenger programme, including a 5,000-account Ubiquity cohort.
SimONE demonstrated that structured digital engagement can create both better customer context and measurable recovery outcomes.
SimONE operates as an intelligence and engagement layer, allowing institutions to preserve their existing ledger and operational systems.
Founder's thinking
“I write about the forces that quietly reshape household balance sheets, institutional risk and public policy. Because a rate hike in one market can become a missed payment thousands of kilometres away.”Kaveer Beharee
Loading the complete Substack archive…
Clear answers
Consumer financial vulnerability intelligence is the continuous interpretation of engagement, capacity, intent and behavioural signals to understand how a consumer’s ability to pay is changing, why it is changing and what governed intervention should happen next.
SimONE is Ubiquity AI’s real-time consumer financial vulnerability intelligence layer. It helps cities, retail lenders and utilities understand changing financial vulnerability, adapt customer journeys and select a governed next action before traditional collections escalation.
The Financial Vulnerability Risk Scoring Index is an algorithm. It combines structured conversational responses with observed behaviour to categorise a customer’s financial vulnerability into one of ten bands, then clusters customers into treatment options. It supports segmentation and journey decisions and is not presented to the customer.
SimONE is built on a compliance technology architecture. Before anything goes live, the compliance guardrails are set upfront: what may be said, when, through which channel and which actions are permitted. Everything that follows is governed by those rules, with traceable inputs and outputs. Because compliance is designed into the foundation rather than reviewed at the end, SimONE can be deployed rapidly even in the toughest regulatory environments.
No more complex than sharing data with any other vendor. SimONE sits before and alongside your existing ledger and collections systems, so nothing needs to be replaced, and it is built for rapid deployment.
A missed payment is rarely about one thing. Customers who feel judged or pressured tend to disengage, while customers who are asked about their circumstances and treated with respect are more likely to respond, explain what has changed and commit to a plan they can keep. Research on debt and dignity, and the experience of collections practitioners, point in the same direction: respectful treatment is associated with better repayment outcomes. SimONE is designed around this. It understands the customer’s situation first, then selects a governed next action. In SimONE’s regulated-lender pilot, structured engagement delivered a Net Promoter Score of 74 and a 4.9% promise-to-pay rate.
No. SimONE sits before and alongside existing systems. It adds customer context, vulnerability intelligence and adaptive engagement without requiring an institution to replace its core ledger.
AI supports analysis, scoring, segmentation and journey adaptation. Consequential customer actions remain governed by deterministic policy rules, with traceable inputs and outputs.
In an environment that demands deterministic outcomes, keeping LLMs out of the decision path is a deliberate advantage. It improves auditability and governance, because every outcome traces back to a defined rule. It improves transparency, because the same inputs produce the same result. It removes variable token costs from the equation, so pricing stays predictable. And it mitigates risk for both our clients and their customers.
Start before collections
Explore how SimONE can add real-time consumer financial vulnerability intelligence and adaptive engagement to your revenue environment.